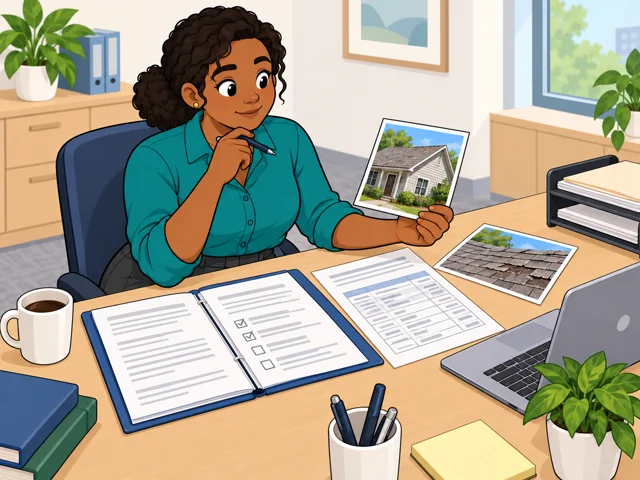
Check records against the application
You check the building's condition and value in property records against the application to judge its risk.
Career profile
Insurance underwriters decide which risks their company accepts and set the terms of coverage.
Would you agree to insure this building? Answering means studying the evidence, asking for anything missing, and making a call you can defend to others.
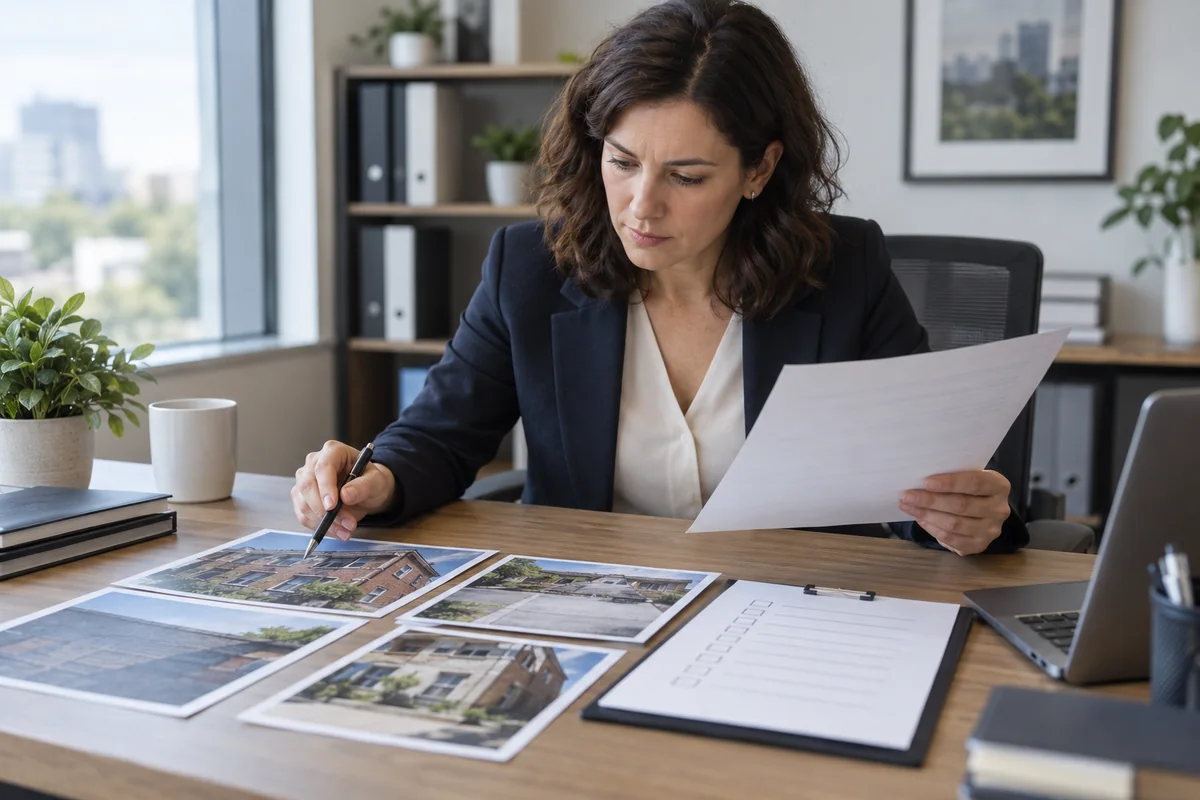
You check the building's condition and value in property records against the application to judge its risk.
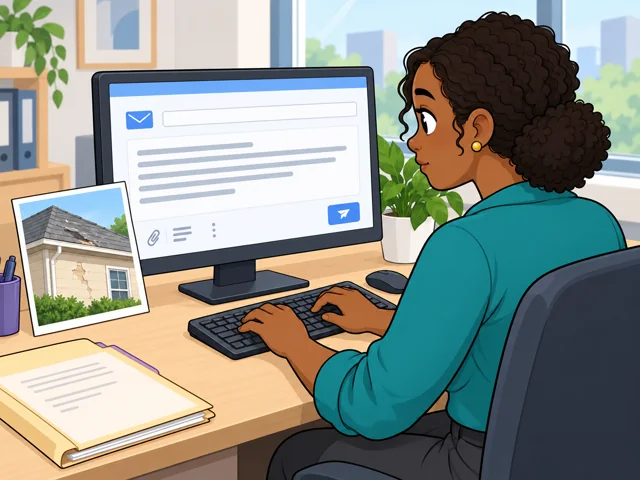
When your records leave the building's condition unclear, you email a field representative for more details.
Look over the software's suggestions before you choose the coverage and the premium, the price charged for it.
Whenever you turn down a risk or change its coverage terms, tell the insurance agent why.
United States
United States · May 2025
United States · 2025–2035
Quick orientation
Related insurance experience sometimes provides another route.
National median; hourly equivalent $39.12.
About 6,800 openings annually, all from replacing workers who leave.
In some life-underwriting systems, software makes scanned medical records searchable and points you to relevant passages.
People assess ambiguous cases and interpret evidence that needs closer scrutiny.
As more decisions become automatic, the mix of applications left for people may change.
Pay in context
Use the national figures as a comparison point, not a starting-salary promise.
The median was $81,370 annually, equivalent to $39.12 an hour. The 10th and 90th percentiles were $55,530 and $145,160. These mark positions in the wage distribution, not beginner and senior salaries.
Annual medians were $91,290 at health and medical insurers, $80,740 at agencies and brokerages, and $80,210 at direct insurers excluding life, health, and medical insurance.
New hires usually begin with a senior underwriter supervising their work.
After entry
This starts where the entry routes leave off: early work, growing capability, and advancement or specialization.
Use training cases, classes, and feedback from a mentor to learn how the company evaluates applications.
Learn customers' coverage needs in detail and build working relationships with the agents who bring you applications.
Advance toward senior underwriter or underwriting manager; employers may require certification.
Office analysis comes with relationship work: you learn businesses' coverage needs and work with agents. Technical knowledge and explaining the offer both matter.
Cases requiring medical evidence can involve lengthy health records. Search tools help you find relevant history, but interpreting complicated records takes sustained attention.
Try it
Invent a small shop applying for property insurance. List what you would ask about the building and possible losses. Then write a short accept-or-decline recommendation and name the missing fact most likely to change it. Notice whether you enjoy making a decision from incomplete evidence.
Stay safe: Use fictional details; this is a reasoning exercise, not an insurance quote.